Insuring a Houma Home and Family
What we look at first in Houma. Wind, water and the road.
Every policy is different, but the same few questions come up again and again with Terrebonne and Lafourche customers. Here's how we think about them.
Hurricane season and named-storm deductibles
Hurricane Ida made landfall near Port Fourchon on Aug. 29, 2021 and hit Houma hard. Hurricane Francine made landfall in Terrebonne Parish in September 2024. Coastal homeowners policies commonly carry a separate percentage deductible for named storms or hurricanes, for example 2% or 5% of the dwelling limit. Read your declarations page so you know your number before the next storm. If you're replacing a roof, the Louisiana Fortify Homes Program offers grants of up to $10,000 toward a FORTIFIED roof, and FORTIFIED roofs earn required discounts on the hurricane portion of your premium. Amounts vary by insurer and region. If you can't find coverage elsewhere, Louisiana Citizens is the state's insurer of last resort.
Flood zones in Terrebonne and Lafourche
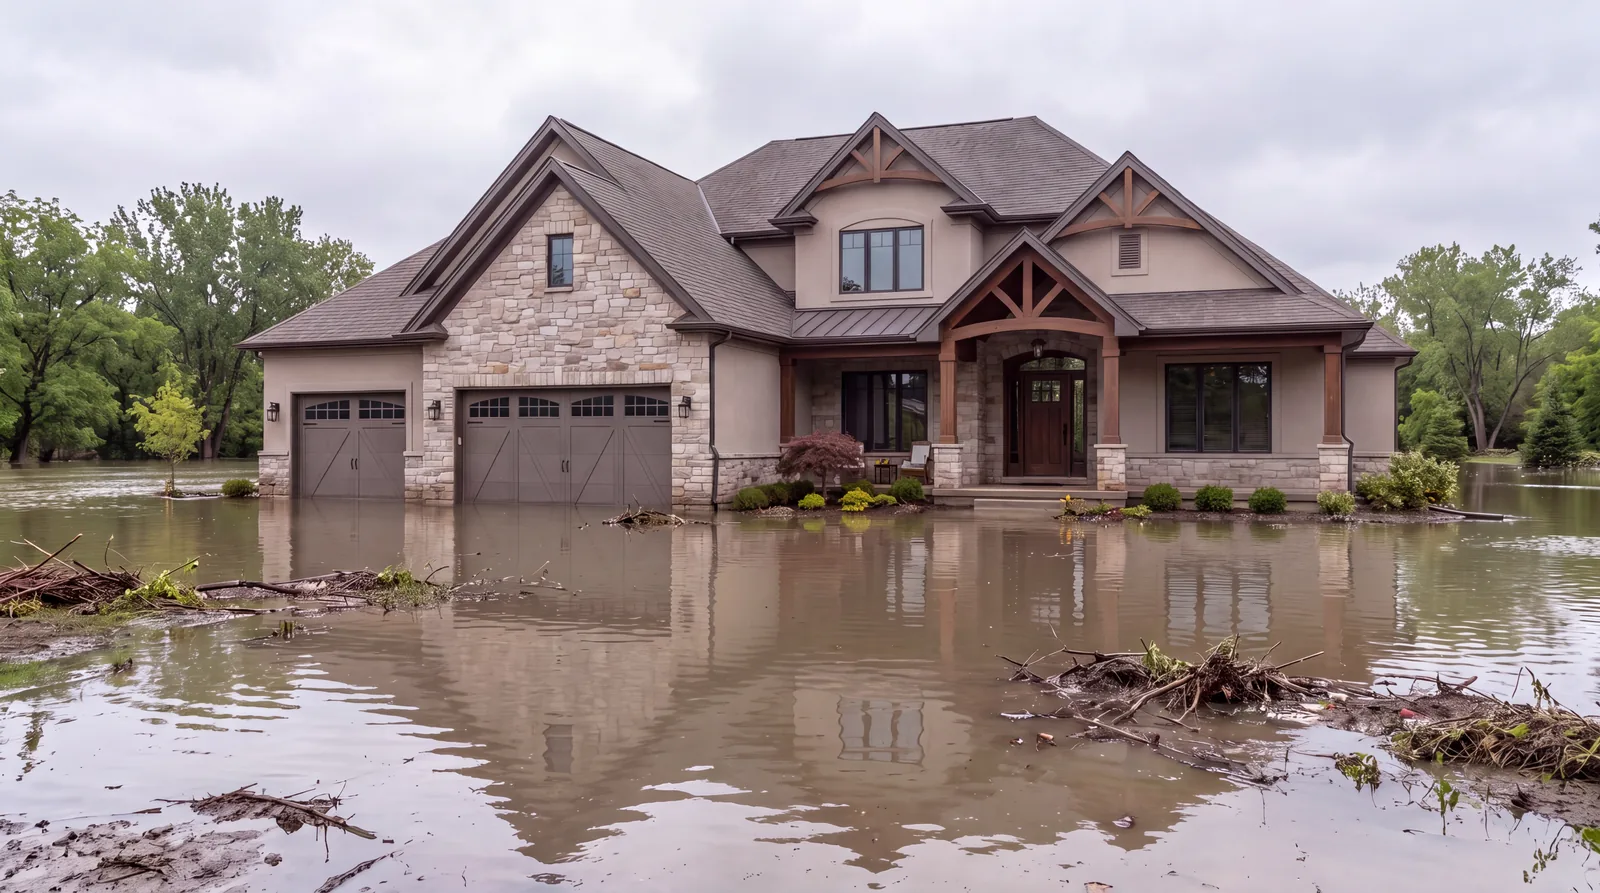
Much of Terrebonne Parish is in FEMA high-risk flood zones. Standard home, condo and renters policies exclude flood, so it needs its own flood policy. You can buy a government-run NFIP policy through an insurance agent. NFIP limits are $250,000 for the building and $100,000 for contents, and there's a 30-day waiting period in most cases. Check your zone instead of assuming, and don't wait for a storm to form. The same applies to condo and renters policies.
Driving in and out of Houma
Louisiana's auto minimum is 15/30/25: $15,000 of bodily injury coverage per person, $30,000 per accident and $25,000 of property damage. Your insurer must offer uninsured motorist coverage at your liability limits, and turning it down takes a signed UM rejection form. Under the 2025 reforms, the No Pay, No Play threshold was raised to $100,000, and a driver found 51% or more at fault can't recover damages. Plenty of Houma drivers commute to Thibodaux, Morgan City and beyond, and the minimum often doesn't go far after a serious crash. We'll show you what higher limits and UM coverage may cost before you decide. If you have a home and assets to protect, an umbrella policy adds another layer on top.
Houma businesses and rental owners
David is a small business owner himself. We write business insurance for local small businesses and landlords and hosts coverage for rental homes, so your personal and business policies can sit with one local office. Coverage is subject to terms, conditions and availability.