Home / Umbrella Insurance

Louisiana Umbrella Insurance: One more layer between a lawsuit and everything you own.

An personal umbrella policy adds extra liability above your auto, home and boat policies. Your local agent in Houma, Raceland and Lafayette lines up every layer so there are no gaps.

25+ YearsIn the Community
4.6Stars, 451 Verified Reviews
LocalInsurance Agency
3 OfficesHouma, Raceland & Lafayette
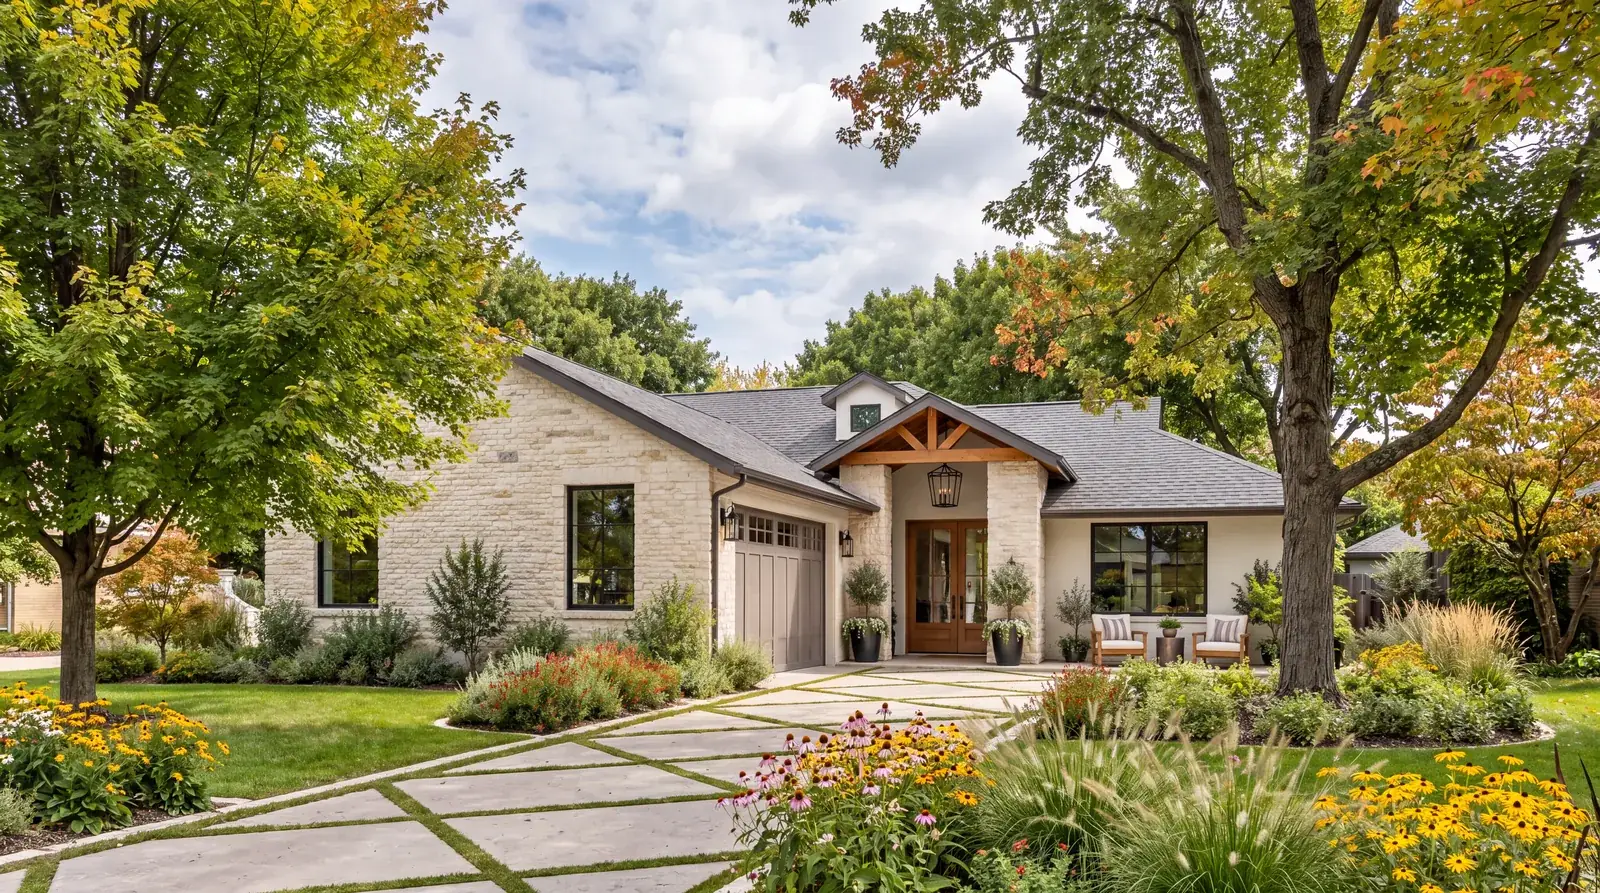
A single-story stone family home with a landscaped front yard
The Quick Answer

A personal umbrella policy adds extra liability coverage above your auto, home and boat policies. Umbrellas are typically sold in $1 million increments and kick in when a serious claim runs past your underlying limits. Depending on the policy, an umbrella may cover bodily injury, property damage and some personal injury claims such as libel or slander, and it can help with legal defense costs. Louisiana's auto liability minimum is just 15/30/25 ($15,000 per person, $30,000 per accident for injuries and $25,000 for property damage), far below what a serious injury lawsuit can cost. An umbrella requires minimum underlying limits on your auto and home policies, so the layers need to line up. It generally doesn't cover your own property or business activities. Ohlmeyer Insurance is David Ohlmeyer Jr.'s local insurance agency, with offices in Houma and Lafayette, offering the personal umbrella policy. Call (985) 876-0116.

Sold in
$1 million increments, typically
Sits above
Auto, home and boat liability
Not for
Your own property or business activities
Free quotes
(985) 876-0116
Louisiana Umbrella Insurance, The Short Version

Your auto and home policies have a ceiling. An umbrella raises it.

Every auto and home policy has a liability limit. Most of the time, that's plenty. But one bad moment can create a claim much bigger than the limit: a multi-car wreck on I-10 or US-90, a guest badly hurt at a crawfish boil by the pool, a dog bite that needs surgery. When the damages run past what your policy pays, the rest can come from you, including your savings, your home equity and even future wages.

A personal umbrella is a separate liability policy that sits on top. Here's a round-number example. Say you cause an accident with $850,000 in damages and your auto liability limit is $300,000. Without an umbrella, the $550,000 difference is your problem. With a $1 million umbrella above the auto policy, that gap may be covered, subject to the policy terms.

Louisiana's minimum auto liability limits, 15/30/25, are among the lowest numbers you'll see on a policy, and they're far below what a serious injury claim can cost. Under the 2025 reforms, a person found 51% or more at fault can't recover damages, and below that, recovery is reduced by their share of fault. If you cause the crash, the other side's damages are yours to answer for. That's why an umbrella is usually paired with higher limits on the policies underneath it.

Umbrella coverage tends to cost less than people expect for the protection it adds. We set up the personal umbrella policy alongside your home and auto coverage so the layers fit together, for families in Houma, Thibodaux, Morgan City, Lafayette, Broussard, Youngsville and across Terrebonne, Lafourche and Acadiana.
What a personal umbrella may cover. And what it usually leaves out.

Coverage depends on the policy, so read these as the typical pattern. We'll walk through your actual wording with you.

Typically covered
Injury

Bodily Injury Liability

Someone is hurt and you're legally responsible: a car accident, a fall on your steps, a dog bite. The umbrella can pay above your auto or home liability limit once that limit is used up.

Typically covered
Damage

Property Damage Liability

Damage you cause to someone else's property, like a pileup involving several vehicles or a boat that slams into a neighbor's dock. The umbrella picks up where the underlying policy stops.

Depends on the policy
Personal Injury

Libel, Slander & Similar Claims

Many umbrellas include some personal injury coverage, such as claims of libel, slander or false arrest. A heated online review or a neighborhood dispute can turn into a lawsuit. Coverage varies, so ask before you assume.

Often included
Defense

Legal Defense Costs

Many umbrella policies help pay defense costs for a covered claim. Even a lawsuit you win can be expensive to defend.

Not covered
Your Stuff

Your Own Property & Injuries

An umbrella is liability coverage. It doesn't repair your house, car or boat after a hurricane, or pay for your own injuries. That's what your home and auto policies are for.

Not covered
Business

Business Activities

Personal umbrellas generally exclude business activities. If you own a business, its liability belongs on a business insurance policy, and we can talk through that side too.

Are your liability limits ready for an umbrella?

Send us your auto and home declarations pages. If your auto is sitting near Louisiana's 15/30/25 minimum, we'll show you what it takes to raise it and add an umbrella on top.

How It Works

Three things to understand before you buy.

1. It's sold in $1 million steps

Personal umbrellas are typically sold in $1 million increments. Many households start at $1 million. If you have significant assets, rental properties or a young driver, a higher limit may be worth pricing. We'll show you what each step adds to the premium.

2. It requires minimum underlying limits

An umbrella doesn't replace the liability on your auto, home and boat policies. It sits on top of them. Each underlying policy has to carry a minimum amount of liability first. If your auto policy is at Louisiana's 15/30/25 minimums, for example, you'd generally need to raise it before an umbrella can be added. If an underlying limit drops below the requirement, you could end up paying the gap yourself, so we check these at every renewal.

3. Every vehicle, home and boat should be listed

The umbrella needs to know what it sits over: every car, every home you own or rent out, and any boats or recreational vehicles. A bass boat or a rental house that isn't listed can leave a hole right where you need coverage. We'll make a simple list together and match it to your policies, including any RV or boat coverage.

Who should seriously consider an umbrella. Probably more people than you'd think.

If you have something to protect, or something that raises the odds of a claim, an umbrella is worth a conversation.

Own a business too?

A personal umbrella generally excludes business activities. Your business needs its own liability coverage, and we can review both sides with you so nothing falls between them.

Louisiana umbrella insurance questions. Straight answers.

What is umbrella insurance?

A personal umbrella is extra liability coverage that sits on top of your auto, home and boat policies. When a serious claim runs past the liability limit on one of those policies, the umbrella can pick up where it stops, up to the umbrella's own limit.

Umbrellas are typically sold in $1 million increments, and they can also help with legal defense costs, depending on the policy. We offer a personal umbrella policy, and we can set it up alongside your other coverage.

Why does Louisiana's 15/30/25 auto minimum matter for an umbrella?

Louisiana's minimum auto liability is $15,000 per person and $30,000 per accident for injuries, plus $25,000 for property damage. A serious crash with injuries can produce a lawsuit many times larger than that, and anything above your limits can come from your own assets.

An umbrella requires higher underlying auto limits first, so adding one usually means raising your auto liability and then stacking the umbrella on top. Together they give you far more protection than the state minimum.

How much umbrella coverage do I need?

A common starting point is enough to cover what you own and what you'd stand to lose, including home equity, savings, investments and future earnings. For many households that's $1 million. Others with more assets, rental properties or a teen driver go higher.

There's no formula that fits everyone. We'll talk through your assets and your risks and show you what each extra million adds to the premium.

What are required underlying limits?

An umbrella expects your auto, home and any boat policies to carry a certain amount of liability first. You need to keep those limits in place for the umbrella to work as designed.

If an underlying limit drops below the requirement, you could end up paying the gap between them yourself. We'll line the layers up so there's no gap and check them at every renewal.

Does an umbrella cover my boat?

It can extend over your boat's liability, as long as the boat is listed and its own policy carries the required underlying liability limit. A wake that swamps another boat or a passenger hurt on a fishing trip can turn into a large claim.

The umbrella covers liability only. Damage to your own boat belongs on the boat policy itself.

Do I need an umbrella if I have a pool?

It's worth a serious look. Pools, trampolines and dogs are some of the most common sources of injury claims at home, and a drowning or diving injury can lead to a claim far larger than a typical home liability limit.

An umbrella adds a layer above your home liability. Tell us about the pool and any fencing or safety features up front so the coverage is written correctly.

Do I need an umbrella if I own rental property?

It's worth a serious look. A tenant or guest injured at a rental can bring a claim that runs past your landlord policy's liability limit. An umbrella can extend over rental properties that carry the required underlying liability.

If the rentals are owned by an LLC, ask us how the umbrella and the named insureds line up. See our landlord insurance page for more.

What doesn't a personal umbrella cover?

It generally doesn't cover damage to your own property, your own injuries, intentional acts or contractual liability. It also generally excludes business activities.

If you own a business, its liability belongs on a business insurance policy. Exclusions vary by policy, so ask us before you assume something is covered.

Still have questions? Call (985) 876-0116. We'll give you a straight answer.

Protect what you've built.
Local coverage, local service.

Tell us about your home, your cars, your boat and anything else you own. We'll check your underlying limits and put together an personal umbrella policy quote that fits on top.